The implementation of complex investment solutions can often feel more rewarding as complexity can be mistaken for value and quality. Simpler solutions, on the other hand – those that can be easily tested and turned into a robust and repeatable process – are the ones that tend to outperform over the long term.
Indeed, the same principle can be applied to most aspects of our lives. Simpler solutions tend to be the ones that provide us with scalability, while the more complex ones tend to be too fragile or too convoluted to be adopted en masse.
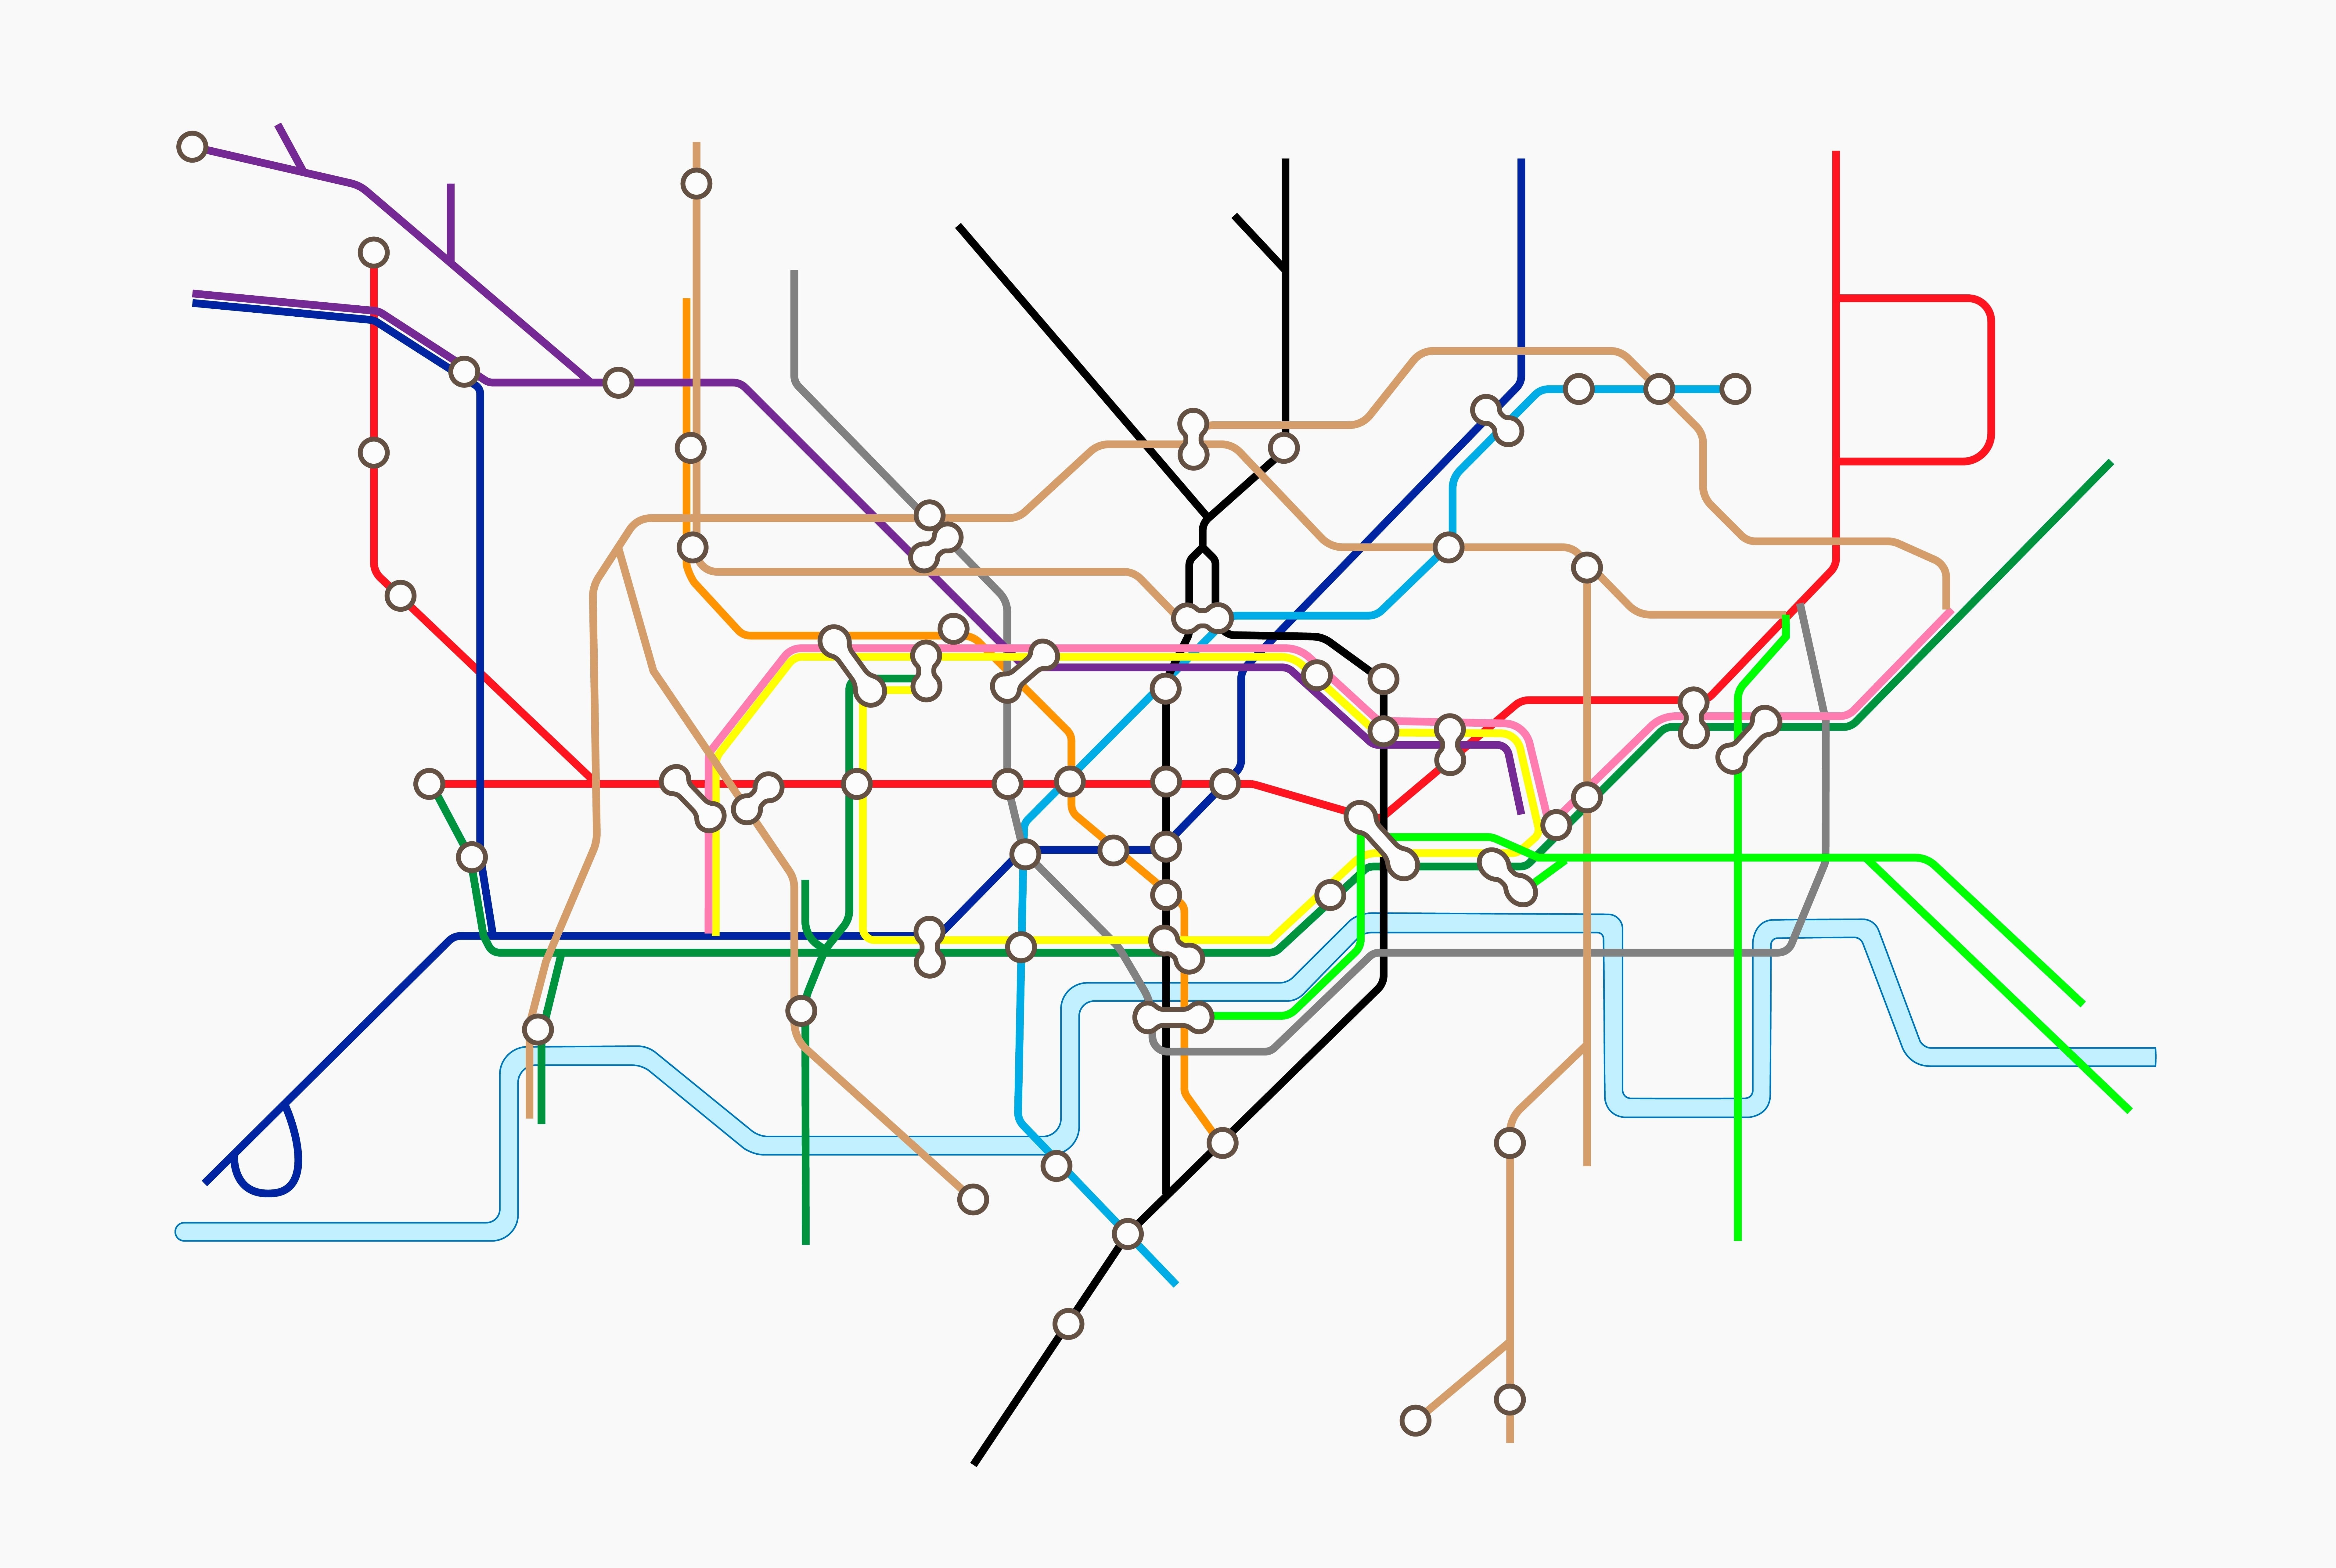
Take the London Tube map as an example. The map we all associate with underground transport not just in London but across the world was developed by Harry Beck in 1933 to update the more topographically correct versions that were unnecessarily complicated for the users.
Beck proposed a new design that only used straight lines and 45-degree angles – forgoing geographical fidelity in favour of clarity. The simplicity of his design was so well-received that other countries implemented it to map their underground networks.
There are three key areas in which additional complexity does not necessarily lead to better investment outcomes – but what can this mean for advisers and investment professionals when constructing or selecting investment solutions?
“Complexity might appear attractive as it often sounds sophisticated, yet it does not always translate into better investment outcomes.
Market noise v investment skill
When retail investors are drawn towards trading, they often seek complex strategies that supposedly allow them to predict future market moves. Advisers and investment professionals will have likely seen this first-hand. Imagine a screen with four or five colourful indicators, all showing one thing – the past price movement of an instrument. This is how trading is often presented to the public.
On the other hand, many seasoned traders – whether working on their own account, at a proprietary desk or on a trading floor – tend to gravitate towards ‘reading the tape’, that is to say reading the price. As simple as it sounds, a security’s current price could act as a better explanation of the past, present and future. An understanding of behavioural finance and market behaviour around specific prices could provide clues about the future of market moves.
Chat with Traders is a podcast where the hosts interview a wide range of professional traders. At the time of writing there are 330 episodes. While not every episode discussed the ability to read the price as the key to a successful investment strategy, it has emerged as a common theme across multiple interviews. Meanwhile the need to use complex indicator-based systems hardly ever came up – suggesting complexity may not be as important to successful trading as we might assume.
This preference for simpler approaches is not limited to individual traders. The same principle can often be observed across the wider investment industry – with one of the most widely cited examples coming from a 10-year wager between Warren Buffett and the hedge fund industry …
Hedge funds v long only
It was back in 2007 when Warren Buffett bet against Ted Seides from Protégé Partners that the US equity market, represented by the Vanguard S&P 500 index tracker, would outperform the return of the hedge fund industry, represented by five funds of hedge funds, over 10 years and net of fees.
The bet captured the 10 calendar years from 2008 to 2018 and, on paper, hedge funds had a good chance of coming out on top. They clearly have an advantage in terms of investment and borrowing powers, including the ability to go short and leverage investments.
There were, however, three primary factors that did not play in hedge funds’ favour. First, statistically, markets go up more than they go down making short investing less lucrative when not timed precisely. Second, hedge funds usually charge much higher fees compared with index funds. And, last but by no means least, is the fact that hedge funds employ more complex strategies that would often only work in specific market conditions.
At the start of the bet, Buffett assessed his probability of success at 60% but the S&P 500 went on to deliver 7.1% annualised over 10 years, while the portfolio of five funds of hedge funds delivered only 2.2% over the same period.
For advisers and investment professionals, it is a useful reminder that high fees and sophistication are not always the predictors of outperformance. The same lesson can also be applied to investor behaviour. Even relatively straightforward investment strategies can become more complex when investors attempt to react to every twist and turn in the market.
Tactical market timing v long-term strategic positioning
How often have you found yourself, or a client, wanting to act on negative newsflow suggesting a market crash was around the corner, or felt the urge to buy something after it enjoyed a period of strong performance? These are natural emotional responses to stress – akin to the ‘fight or flight’ response.
Loss aversion and performance chasing often lead to poor investment outcomes over the long term. Multiple studies – Trading Is Hazardous to Your Wealth, An Empirical Examination of Fund Investor Timing Ability and (maintaining the underground theme) Morningstar’s Mind the Gap, to pick out just three – have been published over the years analysing investors’ behaviour in this regard.
They compare those who made more changes to their portfolios and who tried to tactically time the market with those who took a more strategic approach with fewer trades and a more static exposure – and their findings suggest market timing typically detracts from longer-term returns, reinforcing the value of a disciplined investment process.
Investing often rewards discipline rather than complexity – and, while complex strategies can outperform in some market environments, they find it harder to do so consistently. Complexity might appear attractive as it often sounds sophisticated, yet it does not always translate into better investment outcomes.
This is not to say that there is no place for complexity in financial markets. Financial markets are complex systems by nature – however, complexity often works in relation to specific market scenarios and should only exist when it has the potential to add genuine value, rather than being complex for complexity’s sake or to justify an increase in cost. It can otherwise reduce transparency and create more opportunities for error.
In a world where information is in ever greater abundance, it is all too easy to make investment strategies more complex than they need be. Yet there is value in simplicity and in knowing which information is best left out – particularly when building investment solutions that need to be understood, explained and repeated over time.
Dmitry Konev is head of fund management at Margetts Fund Management