The week that was …
Economic round-up
UK economy surprises with 0.1% growth in August
The UK economy unexpectedly expanded in August, after growing faster than initially estimated over the summer. The Office for National Statistics said GDP increased by 0.1% over the month – a slowdown from the 0.4% rise in July but well ahead of economists’ consensus forecasts for a contraction of 0.1%. June’s growth estimate was meanwhile revised up to 0.4% from 0.3% previously. Read more from the Times here
Four rate rises unlikely – Bank of England hawk
The Bank of England is unlikely to carry out the four interest-rate rises currently being predicted by financial markets, according to the central bank’s chief economist Huw Pill. A consistent supporter of more monetary tightening throughout this year, Pill still said he was “sceptical” about investors’ expectations in a speech at the International Monetary Fund’s annual meeting in Bangkok. Read more from the Times here
US inflation up more than expected in September
US inflation rose to 3.7% in September as the war in Iran drove a rebound in energy costs. This was up from 3.4% in August and ahead of the 3.6% consensus forecast by economists surveyed by Bloomberg. Core inflation, which strips out volatile food and energy prices, also came in ahead of Wall Street expectations, rising to 2.6% from 2.4%. Read more from the FT here
Gas station receipts boost US retail sales
US retail sales increased 0.8% by value in September, following a revised 1.3% gain in August. Sales excluding motor vehicles and gas, however, rose only 0.2% over the month. The value of gas station purchases increased 6.4%, while consumers pulled back spending on areas such as hobbies and building materials. Read more from Yahoo Finance here
Commodities prices push up inflation in China
China’s producer prices rose at their fastest pace in more than four years over September while consumer inflation edged up. High prices for oil and commodities lifted factory-gate costs, although weak domestic demand helped to minimise broader price pressures. Read more from Reuters here
Markets round-up
Asian AI stocks drop on debt concerns …
South Korea’s leading share index, which has become a proxy for the AI trade, dropped sharply as concerns about the massive debt-fuelled investment in artificial intelligence led to a sell-off in related shares. The Kospi index closed down 7.6% last Thursday – a seventh consecutive daily drop and its lowest close since April. Japan’s Nikkei 225 and Taiwan’s Taiex indices also slipped. Read more from the Times here
… and major US indices fall …
The key US Nasdaq Composite and S&P 500 indices ended the week lower, with falls led by AI-related stocks. While also lower on the day, the Dow Jones Industrial Average was still able to record a second straight weekly gain. Read more from Investopedia here
… as FTSE 100 viewed as defensive choice
Britain’s blue-chip stocks enjoyed their best week in six months as investors flocking to defensive sectors to offset the rout in AI-linked stocks. Chancellor John Healey’s reassurances on fiscal discipline also helped risk appetite. UK’s large-cap ETFs attracted $3.38bn (£2.54bn) in estimated net inflows over the year to date – already the biggest annual total since 2020, according to data from Morningstar. Read more from Euronext here
CoreWeave sees shares tumble
CoreWeave, the debt-laden cloud-computing company backed by Nvidia, lost nearly $10bn in value last week as investors fretted it could be the “canary in the coalmine” for the AI industry. The group’s shares dropped by a fifth over the week as the interest charged on its debt spiked. Read more from the Times here
MSCI downgrades Indonesia’s EM status
Indonesia is no longer worthy of ‘emerging market’ status, MSCI announced on Friday as it outlined plans to remove the country’s stockmarket from a suite of indices. The shock move sparked the steepest one-day drop in Jakarta shares since 1998. Indonesia’s benchmark stock index was already the world’s worst performer for the year to date. Read more from Reuters here
“With bonds, clients might reasonably ask why wealth managers are including an asset class that purports to lower their risk but, in recent years, has done nothing but lower their returns.
Selected equity and bond markets: 09/10/26 to 16/10/26
| Market | 09/10/26 (Close) |
16/10/26 (Close) |
Gain/loss |
|---|---|---|---|
| FTSE All-Share | 5694 | 5859 | +2.9% |
| S&P500 | 7812 | 7659 | -2.0% |
| MSCI World | 4962 | 4907 | -1.1% |
| CNBC Magnificent Seven | 475 | 461 | -3.4% |
| US 10-year treasury (yield) | 5.24% | 5.07% | |
| UK 10-year gilt (yield) | 5.44% | 5.38% |
Investment round-up
FCA targets MPS for CCI disclosure regime
The Financial Conduct Authority is examining whether to bring model portfolios under its incoming consumer composite investments (CCI) regime, which aims to standardise disclosure requirements across all types of authorised funds. The regulator said it had asked firms “whether we should make the regulatory treatment of MPS more consistent with other managed products”.
Managers top up on fixed income – BoA survey
Fund managers have become increasingly positive on the prospects for fixed income, with bonds seeing the largest increase in allocations among major asset classes and sectors in the latest Bank of America global fund manager survey. The research indicated investors have rotated allocations away from banks, US stocks and consumer discretionary into bonds, as well as Japanese and UK stocks and utilities.
Wealthy investors sell assets ahead of Budget
More than a third of wealthy investors have either sold investments or plan to do so ahead of the Budget amid concerns that capital gains tax (CGT) rates could rise, according to research from Wealth Club. The group surveyed 506 clients with an average estimated wealth of £3.15m.
M&G launches private credit LTAF
M&G has launched a £74m private credit long term asset fund (LTAF). The M&G Diversified Private Credit Feeder LTAF aims to provide access to private credit investments across the UK and Europe, including infrastructure, real estate and other assets. It has backing from M&G’s £138bn With-Profits Fund.
Aberdeen asset allocation responds to higher rates
Aberdeen has reined in its convictions on property, government bonds and the US dollar for the next 12 to 18 months, in response to higher interest rates. In the near term, the fund house has projected precautionary “insurance hikes” from the Federal Reserve, Bank of England, European Central Bank and Bank of Japan, rather than the start of a sustained tightening cycle.
Active ETF launch from Franklin Templeton
Franklin Templeton has launched Putnam Investments’ first actively managed ETF in the UK. The Franklin Putnam Focused US Research UCITS ETF, which began trading on the London Stock Exchange on 15 October, provides investors with access to a concentrated portfolio of 30 to 45 US equities selected using Putnam’s fundamental research process.
Sycomore launches European fund
Sycomore Asset Management, part of Generali Investments, has launched a European Strategic Sovereignty fund. The fund, which will invest in listed European companies central to the continent’s economic resilience and industrial autonomy, is classified under Article 8 of the EU Sustainable Finance Disclosure Regulation framework.
Global X launches mining company ETF
Global X has unveiled an ETF targeting global goldmining companies with ‘responsible’ characteristics. The Global X Responsible Gold Miners Ucits ETF has a total expense ratio of 0.55% and is listed on Deutsche Boerse and the London Stock Exchange. It is classified as an Article 8 fund under the EU Sustainable Finance Disclosure Regulation framework.
European ETFs see €37bn of inflows in September
European ETFs and ETCs recorded €37.1bn (£31.1bn) in flows in September, taking the year-to-date total to €355.5bn – more than that for all of 2025, according to the latest data from Morningstar. Equity ETFs attracted €25.5bn, down from €37.5bn in August.
… and the week that will be
All eyes on quarterly earnings …
With the AI trade looking shaky, Wall Street will be focusing on quarterly results due from key players including Meta Platforms. AI-linked stocks – so central to the bull market that just marked its fourth anniversary – have struggled in recent days, with sharp declines in shares of semiconductor companies and tech hardware firms such as Dell Technologies. Read more from Reuters here
… and data-centre bonds
Investors are losing confidence that revenues from the AI boom will be sufficient to support the vast debt piles financing data-centres, pushing bonds backing some of the largest US infrastructure projects into increasingly stressed territory. Prices of bonds issued to fund prominent data-centres where Meta, Nvidia, Oracle and others will become tenants – such as ‘Hyperion’ and ‘Project Excalibur’ – have fallen well below par in recent weeks. Read more from the FT here
The week in numbers
UK inflation: Consensus expectations for the UK’s CPI and PPI data in September is a 3.4% year-on-year rise – up from 3.1% in the previous period – and a 0.3% month-on-month rise, down from 0.5% previously. Core inflation meanwhile is expected to be 2.7% year-on-year, versus 2.6% previously.
UK employment data: Consensus expectations are that the August employment rate in the UK will hold steady at 4.9%, while average hourly earnings will rise 3.8% from 3.9% the previous month.
UK retail sales: Consensus forecasts have the UK retail sales number for September up 0.1% month-on-month and 2% year-on-year.
UK business sentiment: The flash October reading of the UK’s manufacturing purchasing managers’ index (PMI) is forecast to fall to 51.8 from 51.9 in September while the services equivalent is expected to fall to 51.9 from 52.1.
US business sentiment: The flash October reading of the US’s manufacturing PMI is forecast to fall to 55.0 from 55.9 in September while the services equivalent is expected to fall to 58.0 from 58.8.
Japan inflation: Consensus forecasts have prices in Japan rising 2% year-on-year in September, while core CPI rises 1.7% year-on-year.
China GDP: Consensus expectations for China’s Q3 GDP estimate is a 5.2% year-on-year rise – up from 4.3% in the previous period – and a 0.7% quarter-on-quarter rise – down from 0.9% previously.
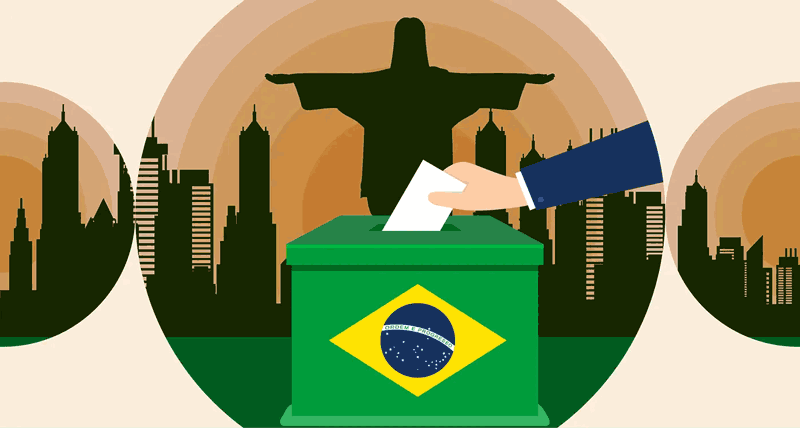
Brazil election: South America’s largest economy will hold a presidential run-off on Sunday, with Flávio Bolsonaro in pole position.
In focus: Why buy bonds?
The pressure on government bonds finally eased last week, as investors grew nervous about the AI trade and retreated to perceived safer havens. This was a cheering moment for multi-asset managers – confirming the normal rules of bond-market investing apparently still apply – while it may also serve to reassure those clients who had started to lose faith in fixed-income allocations in general.
Antony Webb, head of MPS Investment Funds at Quilter Cheviot, says clients are increasingly asking why the team still invest in bonds. Memories of 2022, when the asset class did little to protect investors against volatility in the equity market, remain relatively fresh while 2026 is currently shaping up to be another negative year.
Over the year to date, the average funds in the IA Gilt and IA Global Government Bond sectors are down by 2% and 1.4% respectively. As things stand, then, most investors are still underwater on their bond holdings over five years – by 7% for global bond funds and 23.9% for gilt funds.
At the same time, higher interest rates have left cash rates relatively high – prompting investors to question whether it is worth taking the additional risk on bond markets for an extra percentage or two, when investors can pick up almost 5% from, say, Fidelity Cash. Capital returns may have been unexciting, but that fund has risen 18.6% over five years and experienced no drawdowns.
Rising enthusiasm
It certainly makes bond funds a hard sell at present. Clients might reasonably ask why wealth managers are including an asset class that purports to lower their risk but, in recent years, has done nothing but lower their returns.
In turn, wealth managers should encourage them to look forward rather than back – investors now have a new fixed income reality. Bond fund managers – usually a gloomy bunch – are positively giddy with the opportunities on offer.
Unless inflation accelerates from here, bonds look very cheap in real terms.”
The October edition of Bank of America’s global fund manager survey found professional investors rotating allocations away from banks, US stocks and consumer discretionary – and into bonds. Indeed, the research showed allocations rising by more than 10 percentage points over the month. This came as the proportion of respondents forecasting a rate hike in the coming 12 months fell steeply to its lowest level since May 2025.
“Think about a gilt yield, for example, at 5.4% – or a US 10-year yield currently in excess of 5% – while corporate bonds are even higher,” says Guinness Global Strategic Bond fund manager Craig Veysey.
“If you look at a 6% starting yield, and compound that up over the next five years, that is going to give you a compounded return – purely from income – of 34%. That in itself provides a very solid base of total return for investors, without thinking about the extra alpha you could add from credit selection or from managing the macro-overlay side of the portfolio.”
For his part, Webb argues bonds have the advantage of “certainty in an uncertain world”, adding: “Who is actually using agentic AI in full in their day-to-day personal or business lives? The integration of AI is unknown. What you do know, however, is that you can buy a 30-year bond in the UK for 6% a year. Where have you ever had that? Looking through the exam textbooks, they will say that the long-term run on equities is only around 7% or thereabouts. That is why bond managers are excited.”
Inflation protection?
One of the strongest criticism of bonds these days is they do not provide protection against inflation at a time when such pressures appear to be mounting. Bond fund managers, however, now argue they really could provide more inflationary protection from here.
“A recurring fear in markets is that bonds offer little protection against inflation – and, four years ago, that was a fair charge,” says David Roberts, head of fixed income at Nedgroup Investments, for example. “In March 2022, US core inflation was running at 6.5% while the 10-year Treasury yielded 2.3%.
“As such, lending to the US government for a decade meant locking in a real loss of more than four percentage points a year – and bondholders paid dearly once yields caught up. Today, the reverse is true. At the end of September, 10-year yields stood at 5.3% – more than double core inflation of 2.6%.”
Roberts notes the bond market is already expecting inflation and further rate hikes, adding: “Last week’s 10-year auction – the highest-yielding since November 2000 – drew strong demand, with indirect bidders taking more than 80% of the sale. Unless inflation accelerates from here, bonds look very cheap in real terms.”
A final consideration for investors is that cash has no capital-return potential – at these levels, bonds do.”
One significant exception here may be the corporate bond sector, where spreads are very tight and there is a danger these widen out if growth slows or a risk of recession is priced in. Nevertheless, government bonds have shown their mettle in the latest bout of weakness, rallying in the face of an AI sell-off.
A traditional argument for bonds has been their role as a diversifier yet, in recent times, as inflationary pressures have escalated, bonds have not provided a reliable counterbalance to equity market volatility. Their performance over the past week, however, has suggested they could still have a part to play here.
“The CoreWeave episode shows how quickly sentiment towards AI can turn,” Roberts observes. “If it does fade, the inflationary impulse it has generated could fade with it.” He adds that US consumers are drawing down against buoyant stock portfolios, which means spending is, to some extent, reliant on the continuation of the AI trade. “The past week has shown its fragility,” Roberts concludes. “Bonds offer some protection.”
A final consideration for investors is that cash has no capital-return potential – at these levels, bonds do. With cash, if interest rates fall, investors just receive a lower return. With bonds, that actually serves to push up their prices. After several years during which it has been difficult to find a reason to hold bonds, there increasingly appears a more compelling narrative for their inclusion in portfolios.
In focus: AI, ay, ay
Nobel prize-winning economist Paul Samuelson’s famously joked that “the stockmarket has predicted nine out of the last five recessions” – and something similar could be said of the AI boom. Investors have repeatedly predicted its reversal yet – thus far – every downturn has proved to be just a blip in its upward momentum. Could the most recent sell-off actually be some sort of turning point?
Last week followed a familiar pattern as the technology giants sold off, with the leveraged Kospi index of South Korea leading the falls. That ended the week down at a six-month low as chipmakers slumped.
The sell-off had a number of drivers – the first being sticky US inflation data. US CPI inflation came in marginally ahead of expectations – and high enough to raise expectations of further rate hikes. That in turn cast doubt over future capex spending. With a higher cost of capital, would companies be willing to spend at the same rate?
Then there was the CoreWeave episode and the threat it might be a ‘canary in the coalmine’ for the bursting of the AI bubble. Yields on CoreWeave’s junk-rated bonds duly widened out to 15% to 16% while the cost of credit default swaps, which insure against a company’s default, rose above 1,000 basis points.
Coreweave is a so-called ‘neocloud’ business – a company that offers customers access to computing power without requiring them to build their own data-centres. Even so, it has built up $50bn (£37.5bn) of debt in supplying this capacity and has never made a profit.
The final nail in the coffin for the AI trade was Anthropic’s latest results. On the face of it, a near-50% increase in third-quarter revenue to $16.8bn was an astonishing result – yet it was slower than the pace set at the start of the year. There is a danger this curtails the company’s ability to spend on infrastructure and computing power.
In a normal industry, this would not matter too much, but expectations for AI adoption are high and premised on vast ongoing capital spending. AI also has a PR problem as it will need to convince a wider audience that this is a technology that can benefit them. Until it becomes clearer what it is for – and the sector finds some proper good-news stories on how adoption is genuinely helping people – it will face resistance.
Volatility is a feature of all new technology adoption – and markets are still interrogating the question ‘Is AI a profitable technology?’. The answer to that is by no means yet clear. While the recent sell-off does not yet look like ‘the big one’, it should be a useful reminder that investors need to exercise caution.